

Varo Bank: Online Banking
by Varo Bank, N.A.
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
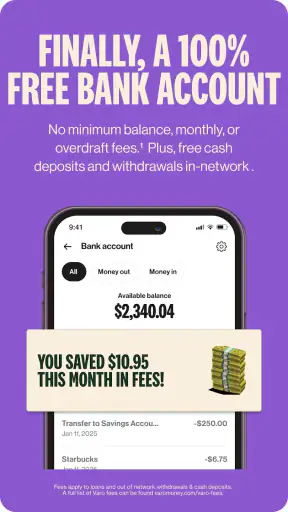
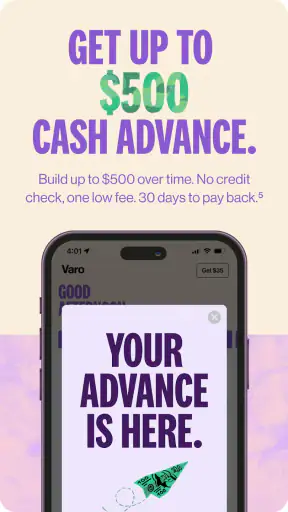
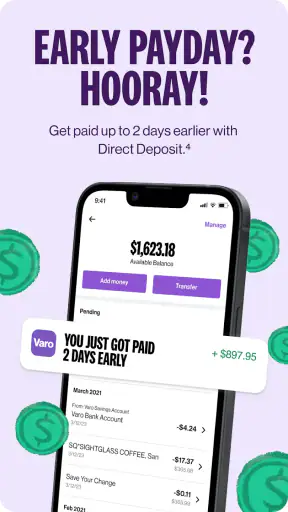
 Analysis by Getfullapps
Managing money from a phone sounds simple until the moment you need to check a balance, move funds, or deal with an unexpected expense while away from home. After spending time with Varo Bank: Online Banking, I found that its biggest strength is also the thing that defines the whole experience: it puts everyday banking in your pocket, but the quality of that experience depends heavily on having a reliable connection when you need it.
This is a free finance app from Varo Bank, N.A., aimed at people who want mobile banking with access to early-payday tools and cash advances. It has earned a 4.5 average from around 245 thousand ratings, with more than 5 million installs, so it is clearly used well beyond a small group of early adopters. I would describe it as a practical banking companion rather than a complete replacement for every financial service. It can make routine money management easier, but it is not equally suitable for every banking situation.
How Varo feels when your money depends on a connection
The first thing I noticed is how often a banking app becomes useful at precisely the wrong time for a weak signal. You may be standing at a checkout, waiting for a transfer to appear, checking whether a deposit arrived, or trying to understand whether you can afford a purchase. In those moments, the app is not just a convenient shortcut. It is the place where you expect a current answer.
That makes connectivity part of the product experience, not a minor technical detail. With a stable mobile connection or Wi-Fi, opening the app and checking your financial position feels straightforward. When the connection is slow, interrupted, or switching between networks, the same task can become uncertain. A delayed screen can leave you wondering whether the information is old, whether an action has completed, or whether you should try again.
I recommend treating the app as a live banking window rather than a pocket folder of stored information. Before leaving for a trip or heading somewhere with unreliable reception, I would check recent activity and make any planned transfers in advance. That small habit reduces the chance of needing an immediate answer in a place where the phone cannot communicate properly with the bank.
Everyday banking works best when the timing is predictable
For ordinary tasks, the appeal is easy to understand. I can imagine using Varo for checking an incoming payment, watching spending throughout the week, or confirming that a bill-related transaction has appeared. The value is not in making banking feel exciting; it is in removing the need to wait until I am at a computer or near a branch.
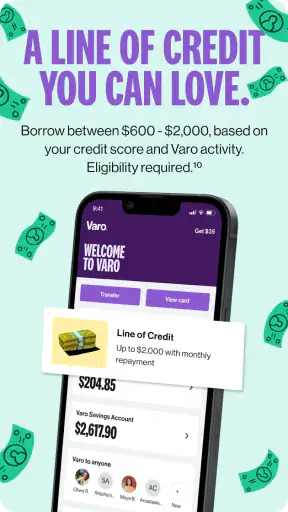
The early-payday positioning is especially relevant to people whose budgets are tight between pay periods. It may help someone plan around incoming money, while the cash-advance angle speaks to short-term gaps. However, I would not treat either option as free money or as a substitute for a sustainable budget. Before relying on an advance, I would read the terms shown inside the app and consider how repayment affects the next pay period. Convenience can hide the fact that a short-term solution still changes the shape of your future cash flow.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
One useful workflow is to separate checking from decision-making. I would first open the app and confirm the latest visible activity, then pause before moving money or accepting an advance. If the connection is unstable, the safest choice is to avoid repeating an action simply because the screen has not refreshed. In financial apps, impatience can create more confusion than the original problem.
Using it on the move
Varo makes the most sense for people who handle much of their financial life from a smartphone. A commuter can check an account before paying for transportation, a freelancer can look for an incoming payment between appointments, and a parent can review available funds while shopping. These are small moments, but they are exactly where mobile banking earns its place.
There is also a psychological benefit to checking activity close to the moment it happens. Instead of postponing money questions until the end of the day, I can use the app to make a more informed decision while the context is still clear. That is helpful for spotting an unfamiliar transaction or noticing that a planned payment has not appeared as expected.
Still, mobile convenience can encourage overchecking. I would not recommend opening the app every few minutes and making spending decisions based on a balance alone. A balance does not automatically explain what is pending, what has already been committed elsewhere, or how upcoming obligations will affect the week. Varo is more useful when paired with a simple personal routine: review activity, account for known expenses, and then decide what is genuinely available.
Travel is another situation where preparation matters. Before going somewhere unfamiliar, I would make sure the app is installed and usable, confirm that I can sign in, and keep alternative ways of accessing important account information available. I would also avoid making a last-second transfer immediately before entering a low-signal area. The app can be valuable on the road, but it should not be the only plan for an urgent financial decision.
What happens when something goes wrong?
The most frustrating scenario is not necessarily a total outage. It is the ambiguous middle ground: the app opens, part of the information appears, and an action seems to be waiting. This is where a connection problem can feel like a banking problem. If a transaction screen does not update, I would first wait rather than tapping repeatedly. Then I would check whether the phone has actually regained service, close and reopen the app if appropriate, and review the account activity before attempting the action again.
That sequence is especially important for transfers or other actions that could be submitted more than once. A slow response does not always mean nothing happened. My practical rule is simple: verify the account state before retrying a financial action. If the status remains unclear, I would keep a note of the time and what I attempted, then use the support route available through the app or the bank instead of guessing.
Recovery is also about keeping expectations realistic. A mobile bank can show information quickly when the service is reachable, but it cannot make a weak network behave like a strong one. If I were dealing with a time-sensitive payment, I would start early enough to leave room for checking the result. Waiting until the final minute turns a small connection delay into a much larger problem.
For a new user, I would spend a few minutes learning where recent activity, account details, and help options are located before an emergency occurs. That is a better test than simply opening the home screen once. Familiarity reduces the temptation to make hurried decisions when a payment or deposit does not look immediately clear.
Being careful with mobile data
Banking apps are not the kind of tools I would use casually on an unknown public network. I prefer a trusted connection for signing in and reviewing sensitive financial information, especially when I am in a crowded place. The concern is not unique to Varo; it is a sensible habit for any financial service accessed from a phone.
People with limited mobile data can also use a more deliberate routine. I would avoid repeatedly refreshing the same page, wait for a stable connection before starting a transfer, and review several pieces of information in one session rather than opening the app for every tiny question. This is not about measuring a particular data cost. It is about avoiding unnecessary retries and reducing the chance that a task is interrupted halfway through.
Connectivity can affect privacy in another way: the more often I check money in public, the more aware I need to be of who can see the screen. A quick balance check at a checkout may feel harmless, but account details and transaction descriptions are still personal. I would use the phone’s normal security protections and avoid discussing sensitive information aloud in crowded spaces.
One of the less obvious trade-offs is that immediate access can make financial information feel more certain than it really is. A screen may be current at the moment it loads, but my spending plan still needs to include commitments that have not yet shown up. I would use Varo to gather information, not as permission to spend every dollar displayed. That distinction matters most for users attracted by early-payday access or cash advances.
Who will get the most from Varo?
I think Varo is a strong fit for someone who wants a phone-first way to handle routine banking and values quick access to account information. It is particularly appealing if early access to pay or a cash-advance option could help smooth an occasional shortfall, provided the user reads the conditions and has a repayment plan.
It may also suit people who dislike traditional branch-based routines. The app is free, carries an Everyone content rating, and comes from an established banking developer rather than an anonymous budgeting tool. Its current version is 4.36.0 and requires at least Android 10, which is worth checking before installation if you use an older device. The age rating does not mean every financial decision is suitable for every young user; it simply describes the app’s store classification, while account eligibility and banking requirements still matter in practice.
I would be more cautious about recommending it to someone who wants extensive in-person service, complex business banking, or a broad wealth-management relationship. A conventional bank may be better if you regularly need branch assistance, specialized lending, or a wider range of financial products. Likewise, someone who wants a pure budgeting app with accounts from several institutions may prefer a dedicated money-management tool rather than making one bank account the center of the experience.
How it compares with familiar alternatives
Compared with a traditional bank’s mobile app, Varo’s appeal is its focus on accessible, phone-based banking and short-term cash-flow features. A large conventional bank may offer a broader relationship, more physical locations, or more established options for complex needs. Varo feels more targeted toward people who want the essentials close at hand and who are comfortable handling support and account management digitally.
Compared with a prepaid card app, Varo presents itself as a bank rather than merely a spending interface. That distinction may matter to users who want banking functions in one place, though I would still compare account terms carefully before moving my main income or emergency savings. The right choice depends less on which app looks simpler and more on whether its limitations match the way I actually manage money.
Compared with a dedicated cash-advance service, the banking integration can be convenient because the short-term feature sits alongside everyday account activity. The trade-off is that convenience may make borrowing feel too close to normal spending. I would choose a separate alternative if it offered clearer terms for my situation, a better repayment structure, or support that matched a more complicated financial need.
The most important comparison is not the number of buttons on the screen. It is how well the service fits my habits when money is tight, my connection is unreliable, or I need a human explanation. Varo is attractive when speed and mobile access matter most. Another provider is better when physical support, specialized products, or a more comprehensive financial relationship matters more.
A realistic week with the app
Imagine that I am paid on a Friday but need to cover groceries, transportation, and a utility payment before the next deposit. I open Varo during a commute with a dependable connection, review recent activity, and note what has already left the account. If an early-payday option or cash advance is available to me, I would compare the immediate relief with the effect on my next pay period rather than accepting it automatically.
Later, at the store, I would use the app to confirm my available position before checking out. If the page loads slowly, I would not keep pressing refresh while standing at the register. I would wait for a clear result or use a less time-sensitive payment plan. That may sound overly cautious, but ambiguity is exactly what I want to avoid when the account is connected to real spending.
At the end of the week, I would review the activity again and look for anything I do not recognize. This turns the app from an emergency button into a regular check-in. The connection helps me see current information, but the useful part is the habit of reviewing it calmly and making decisions before a shortage becomes urgent.
My verdict on the connected experience
Varo Bank: Online Banking is a sensible choice for people who want everyday banking to travel with them and who understand that a mobile account is most useful when they plan around connectivity. The app’s free price, strong user response, and more than 5 million installs make it an easy service to investigate, while the early-payday and cash-advance focus gives it a clear identity beyond a basic balance checker.
My recommendation comes with boundaries. I would use it for routine access, monitoring, and carefully considered short-term cash flow, but I would not rely on it as my only plan during a network outage or for complicated financial needs. I would prepare before travel, verify results before repeating actions, use trusted connections, and treat advances as a decision with consequences rather than a bonus.
In the end, the app works best for a person who wants convenience without confusing convenience for certainty. If that describes you, Varo can make mobile banking feel practical and immediate. If you need branches, specialized banking, or a service that remains useful when your phone cannot connect, a different option may be the wiser choice.
Pros
- No monthly fees for basic accounts.
- Access to early direct deposit.
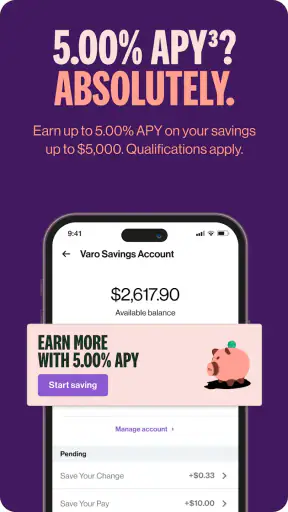
- High-yield savings options available.
- User-friendly mobile interface.,24/7 customer support via chat.
Cons
- Limited physical branch access.
- No joint or business accounts.
- Cash deposits can be inconvenient.
- Overdraft protection is optional.
- Limited international transfers.
FAQs for Varo Bank: Online Banking
What features does Varo Bank offer for online banking?
Varo Bank provides a comprehensive suite of features including fee-free checking and savings accounts, early direct deposit, automatic savings tools, and access to over 55,000 fee-free ATMs. The app also offers budgeting tools, instant account notifications, and secure, easy-to-use mobile deposits to help manage your finances effectively.
Is Varo Bank safe and secure to use?
Yes, Varo Bank employs advanced security measures to protect your financial information. The app uses data encryption, multi-factor authentication, and biometric logins. Additionally, Varo Bank is FDIC insured up to $250,000, ensuring your money is protected in the event of a bank failure.
Are there any fees associated with Varo Bank accounts?
Varo Bank is known for its minimal fee structure. There are no monthly maintenance fees, no foreign transaction fees, and no minimum balance requirements. However, fees may apply for certain services like out-of-network ATM withdrawals, so it’s important to review the fee schedule provided by Varo.
Can I deposit cash into my Varo Bank account?
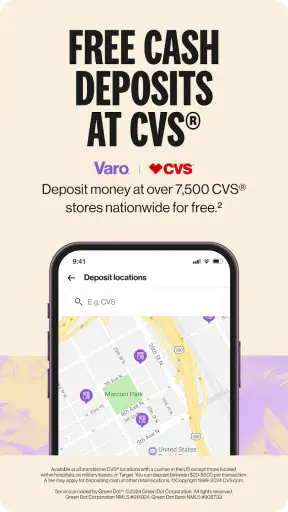
Yes, you can deposit cash into your Varo Bank account. Varo has partnered with Green Dot to allow cash deposits at over 90,000 retail locations nationwide. Keep in mind that while Varo itself doesn’t charge a fee, Green Dot retailers may have their own service charges.
Does Varo Bank offer customer support if I encounter issues?
Varo Bank provides customer support through multiple channels. You can reach their customer service team via phone, email, or through the in-app chat feature. Their support team is available 7 days a week to assist with any questions or issues you may encounter while using the app.

Varo Bank: Online Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@varomoney.com, visit https://www.varomoney.com, or review their https://www.varomoney.com/privacy-legal/.










